Personal financeOct 08, 2026
What a $500K Nest Egg Actually Pays Out Per Month
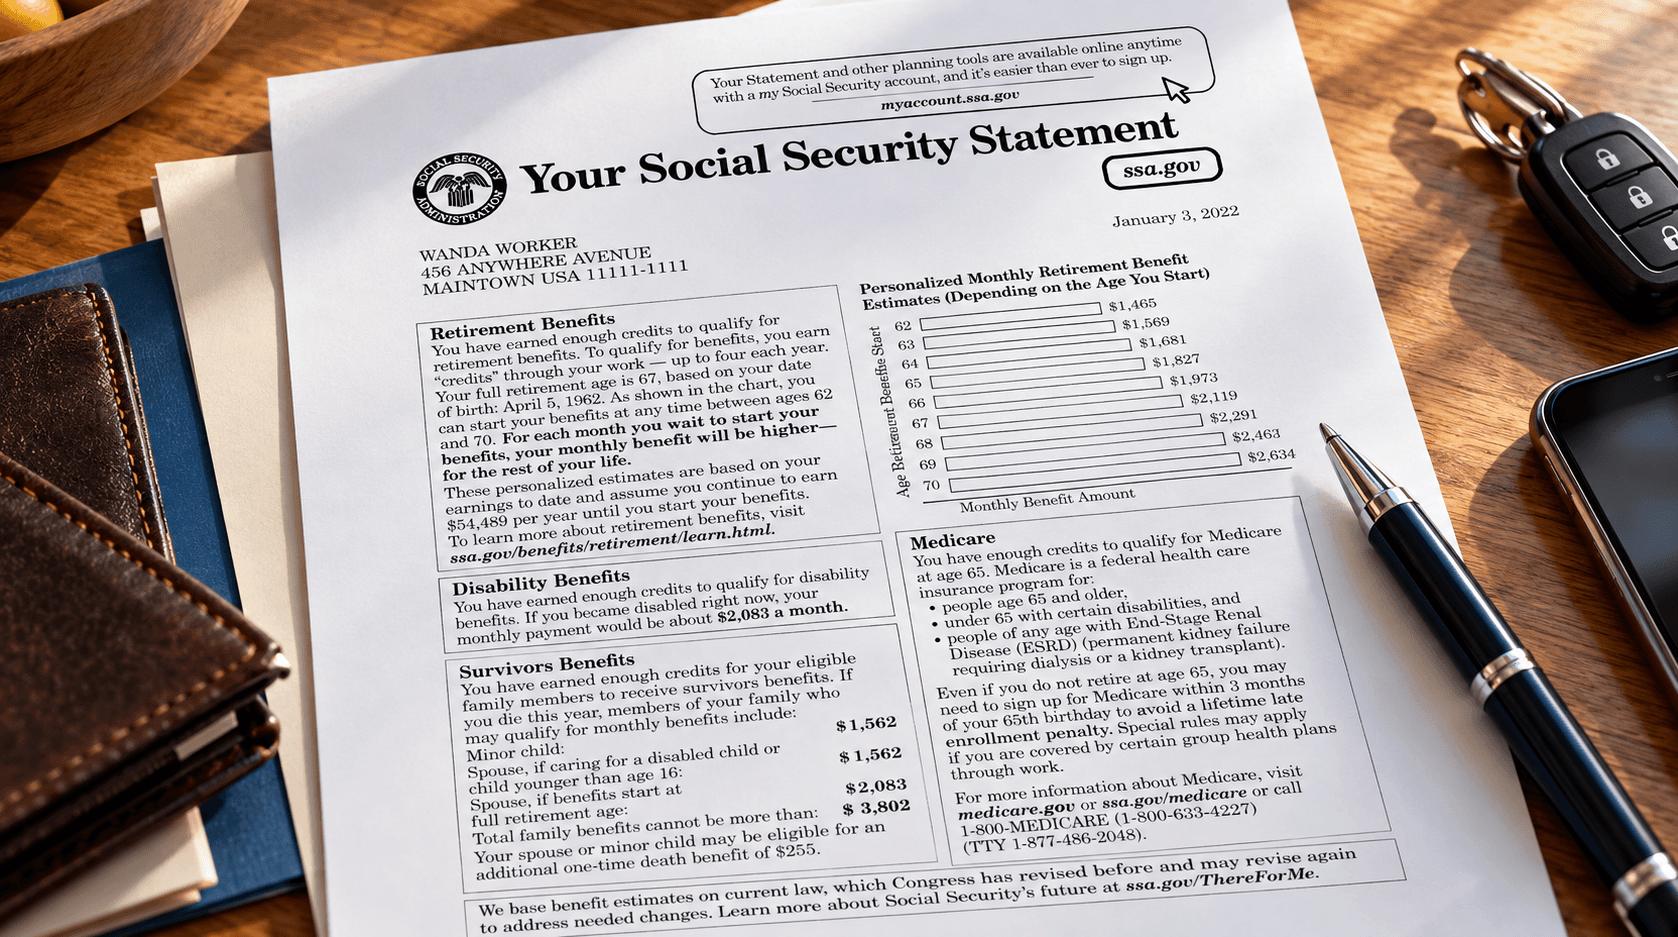
Key takeaways A 4% starting withdrawal on $500,000 is about $1,667 a month before taxes, and Morningstar's current 3.9% estimate is about $1,625 a month, both assuming inflation adjustments over a 30-year retirement. Spending the balance down to zero over 20 to 30 years can produce $2,700 to $3,300 a month in a smooth hypothetical, but those payments don't keep up with inflation and leave nothing if you live longer than planned. Poor returns in the first few years of retirement can do lasting damage, and flexibility in early spending is one of the few levers fully in your control. Taxes depend on account type, so the same $500,000 can produce noticeably different spendable income in a traditional IRA, a Roth IRA, or a brokerage account. Pairing your savings with Social Security and working backward from your monthly spending needs shows quickly whether your plan sits in a sustainable range. For most of your working life, the goal with your retirement savings was simple: keep growing the balance. Then retirement gets close, and the question changes from asking how much you have to what it will pay you every month, because your house payments, groceries, insurance premiums, and the trips you've been putting off all arrive monthly, not as a lump sum. Half a million dollars is a milestone many people work decades to reach, and it feels like it should translate into a clear, comfortable paycheck. The truth is it can produce very different monthly amounts depending on choices you make and conditions you don't control, and the difference between a cautious plan and an aggressive one can run well over a thousand dollars a month. This guide walks through some of the main ways to turn $500,000 into income, shows what each approach pays in hypothetical dollar terms, and labels every assumption along the way so you can see which ones may fit your situation and which may not. Why isn't there one monthly number for $500,000? A savings account balance tells you what you have today, but a monthly income figure is a forecast, and every forecast rests on assumptions. Four of them do most of the work here. The first is how long the money needs to last, since a portfolio that only has to cover 15 years can pay out far more each month than one that has to stretch across 30 or more. The second is what your investments earn along the way, and in what order those returns arrive. The third is whether you want your withdrawals to rise with inflation so your spending power holds steady, and the fourth is how much of each withdrawal goes to taxes and fees before it reaches your checking account. Change any one of those and the monthly dollar figure moves. That's why two retirees with identical $500,000 balances can reasonably land on very different paychecks, and why a single number from a headline or a coworker rarely fits your own plan. The good news is that researchers have spent decades studying exactly this problem, and their work gives you a sensible starting range. Every example in this article uses a $500,000 starting balance, and every figure is a hypothetical illustration rather than a projection of what any particular portfolio will do. How much can you safely withdraw each year? Much of today's retirement income planning traces back to a 1994 paper by financial planner William Bengen, who tested withdrawal rates against actual historical market returns and inflation going back to 1926 instead of relying on long-run averages. His method set the first year’s withdrawal as a percentage of the starting portfolio, then adjusted that dollar amount up or down for inflation every year after. Assuming a portfolio split evenly between stocks and intermediate-term Treasury notes and a need for at least 30 years of income, he found that a 4% first-year withdrawal had never exhausted a portfolio in fewer than 33 years. He described a 5% starting rate as risky and anything at 6% or above as gambling (1) . His 4% starting point is what’s now widely known as the 4% rule, and it remains a common starting guideline for retirement withdrawals (7) . On a $500,000 portfolio, a 4% starting withdrawal comes to roughly $20,000 in the first year, or about $1,667 a month. Bengen’s paper includes an example of a retiree who started with $500,000 and withdrew $20,000, or 4%, in the first year (1) . Divided by 12, that first-year withdrawal works out to about $1,667 a month, a hypothetical figure calculated for this article rather than one stated in the paper. Two details are easy to lose in the shorthand. The 4% applies only to the first year, after which the dollar amount rises with inflation rather than being recalculated as 4% of whatever the balance happens to be. That also means the $1,667 monthly figure is before taxes, because Bengen’s analysis assumed the money sat in tax-deferred accounts (1) . What does more recent research suggest? Morningstar publishes an annual estimate of a safe starting withdrawal rate using forward-looking assumptions about stock returns, bond yields, and inflation rather than purely historical data. Its most recent report put that rate at 3.9% for a new retiree who wants steady, inflation-adjusted withdrawals, defined as the highest starting rate with a 90% probability of money remaining after 30 years. The estimate excludes Social Security and other income outside the portfolio, and it applied to portfolios holding between 30% and 50% in stocks. The same research found that retirees willing to let their spending flex with the market could start closer to 6%, and that older retirees can reasonably spend more (2) . At 3.9%, a $500,000 portfolio supports a first-year withdrawal of $19,500, or $1,625 a month. That's only $42 a month less than the classic 4% figure , which shows how closely the two benchmarks line up for a portfolio of this size. The jump from 4% to 6% adds about $833 a month, but for withdrawals that rise with inflation every year, it also moves you past both Bengen’s 4% finding and Morningstar’s 3.9% estimate and into the range Bengen called gambling (1)(2) . That higher number amounts to a bet that the coming decades of markets will treat you better than the worst stretches of the past did. What if you plan to spend the whole balance by a certain age? The withdrawal rates above are set so the money has a strong chance of lasting at least 30 years, and Morningstar’s estimate specifically targets a 90% probability of funds remaining (2) . Some people would rather plan to use up the entire balance over a set number of years, the way a mortgage pays down to zero. That approach produces a higher monthly payment, at the cost of leaving nothing behind if the plan runs its full course. The figures below assume, hypothetically, a steady 5% annual return compounded monthly, level payments that don't rise with inflation, and a balance that reaches zero at the end of the period. Hypothetical illustration assuming a constant 5% annual return, no inflation adjustments, and no taxes or fees. Real returns vary from year to year. These payments look far more generous than the 4% figure, and that comparison deserves a closer look. The level payment never increases, so its buying power shrinks every year that prices rise. It also assumes a smooth 5% every single year, which no real portfolio delivers, and it leaves you with nothing if you outlive the period you chose. For someone with a pension or substantial Social Security covering essentials, a planned spend-down of part of their savings can be a reasonable choice. As a plan for every dollar you have, it carries real longevity risk. How long does $500,000 last at different monthly withdrawals? You may already know roughly what you'll want to spend each month. In that case, the more useful question runs the other direction, which is how many years a given withdrawal can last. The table below shows two hypothetical scenarios, one where the portfolio earns a steady 5% a year and one where the money earns nothing at all, the way cash in a drawer would. At $2,000 a month, a steady 5% return would cover the withdrawals without touching principal, because 5% of $500,000 is $25,000 a year and you'd be taking $24,000. Push the withdrawal to $3,000 and the same portfolio lasts a little under 24 years, which may or may not be long enough for someone retiring at 62. The 0% column is a reminder of how much work investment growth does in any retirement plan, and why keeping all of your savings in cash carries its own risk. Why does the order of your returns change the answer? Averages hide one of the biggest risks retirees face, which is the order in which good and bad years arrive. This is known as sequence-of-returns risk. When you're withdrawing money every year, a market drop early in retirement forces you to sell more shares at low prices to cover the same expenses, and those shares aren't there to recover when the market turns around. Here's a hypothetical illustration. Two retirees each start with $500,000, withdraw $25,000 at the start of every year, and experience the exact same ten annual returns, eight years of 7% growth and two years of losses (down 15% and down 10%). The only difference is timing. The first retiree hits both losses in years one and two, while the second hits them in years nine and ten. After ten years, the first retiree has about $311,000 left, while the second has about $407,000, a difference of roughly $96,000 from identical returns arriving in a different order. History has its own version of this story. In Bengen’s research, a retiree who started in 1929 with $500,000 saw the portfolio fall below $200,000 by the end of 1932. Deflation had lowered his annual withdrawal from $20,000 to $15,300, but because the portfolio had shrunk so much, that smaller withdrawal now equaled about 7.6% of what remained, up from the 4% he started with (1) . Morningstar's latest research found the same pattern in forward-looking terms, concluding that retirees who hit poor returns in the first five years and didn't trim their spending were much more likely to run out of money than those whose early years were positive (2) . The practical takeaway is that flexibility in the early years carries outsized weight. Bengen found that if his 1929 retiree had cut his 1930 withdrawal by just 5% and stayed at that lower level, keeping his portfolio at 75% stocks, he would have had 20% more wealth by 1949 than if he’d kept spending at the original pace (1) . How does inflation change your monthly figure over time? The 4% rule and Morningstar's 3.9% estimate both assume your withdrawal rises with inflation each year, which means the monthly amount you start with isn't the amount you'll be taking ten or twenty years later. That rising withdrawal is the whole point, because it keeps your spending power roughly level as prices climb. To illustrate a hypothetical example, let’s assume inflation runs 2.5% a year, close to the 2.46% expected inflation rate used in Morningstar’s research (2) . A retiree who starts with a $20,000 annual withdrawal, about $1,667 a month, would be taking roughly $24,977 a year by the tenth year (about $2,081 a month) and roughly $31,973 by the twentieth year (about $2,664 a month) . The paycheck grows in dollars, but it buys less than it did in year one. This is also why the level payments in the spend-down table above can mislead. A flat $2,684 a month for 30 years would, under that same 2.5% inflation assumption, buy noticeably less in year 20 than it did in year one. What do taxes and fees take out of each withdrawal? Every monthly figure in this article so far is a before-tax number, and what reaches your bank account depends heavily on which type of account the money comes from. Withdrawals from a traditional IRA or 401(k) are generally included in your taxable income (3) . Traditional IRA distributions are taxed as ordinary income, while Roth IRA distributions aren’t taxed as long as you meet certain IRS criteria (4) . Money in a regular brokerage account works differently again. When you sell an investment there, only the difference between what you paid (your basis) and what you sold it for counts as a capital gain, and gains on assets held more than a year may be taxed at a lower rate than ordinary income, sometimes as low as 0% (5) . Here's what that can look like in practice. If all $500,000 sits in a traditional IRA and, hypothetically, 12% of each withdrawal went to federal income tax, a $1,667 monthly withdrawal would leave about $1,467 to spend. The same withdrawal from a Roth IRA meeting the qualified-distribution rules wouldn't owe federal income tax at all. Your own rate depends on your total income, filing status, deductions, and state, which is why the mix of account types you hold can shape your spendable income as much as the balance itself. Fees deserve the same scrutiny. A hypothetical 1% annual advisory or fund fee on a $500,000 portfolio comes to $5,000 a year, or about $417 a month. Next to a $20,000 annual withdrawal, that fee equals a quarter of what you're taking out for yourself. That doesn't make paying for advice a mistake, but it's a cost worth weighing against what you receive in return. How do required minimum distributions fit in? If your savings sit in tax-deferred accounts, the government eventually sets a floor on what you must withdraw. You generally have to start taking required minimum distributions (RMDs) from traditional IRAs and most workplace retirement plans once you reach age 73, and Roth IRAs don't require withdrawals while the original owner is alive. Each year's RMD is the prior year-end balance divided by a distribution period from an IRS “Uniform Lifetime Table.” (3) . Using the IRS Uniform Lifetime Table, the distribution period is 26.5 at age 73 and 24.6 at age 75 (4) . On a hypothetical $500,000 balance, that works out to a required withdrawal of about $18,868 at 73 (roughly $1,572 a month) and about $20,325 at 75 (roughly $1,694 a month). Those amounts land surprisingly close to the 4% rule, but they serve a different purpose. An RMD is a tax rule setting the least you must take out , not a recommendation for how much you can safely spend, and you're free to withdraw more than the minimum (3) . The RMD also rises as a share of your balance each year as the distribution period shrinks with age. What does $500,000 look like alongside Social Security? If you also collect Social Security, your savings are only one piece of your monthly income. As of January 2026, the average monthly benefit for retired workers was about $2,088 (6) . Morningstar's safe withdrawal estimates specifically exclude Social Security, so the two sources of income stack on top of each other (2) . In a hypothetical case, a retiree who collects the average retired-worker benefit and takes a 4% withdrawal from a $500,000 portfolio would start with roughly $3,755 a month in combined income before taxes. That's $1,667 from savings and about $2,088 from Social Security. Working the numbers in reverse can be even more revealing. Suppose you expect to need $5,000 a month before taxes and your Social Security benefit matches that same $2,088 average. Your portfolio would need to supply about $2,912 a month, or roughly $34,900 a year, which is a starting withdrawal rate of about 7% on $500,000, well above the range the research above considers sustainable for a 30-year retirement (1)(2) . Seeing that figure in advance gives you room to adjust, whether that means working a little longer, delaying Social Security for a larger benefit, trimming planned spending, or building more flexibility into how you draw down savings (2) . Common mistakes worth avoiding Treating 4% as a fixed percentage of whatever the balance is each year. In Bengen's research, the 4% sets only the first year's dollar amount, which then rises with inflation (1) . Taking 4% of the current balance every year is a different strategy, sometimes called a constant-percentage approach, and it produces a paycheck that rises and falls with the market. Morningstar found that approach can support a higher starting rate precisely because it cuts spending when portfolios decline (2) , so the two methods aren't interchangeable. Planning with average returns instead of a range of outcomes. A steady 5% a year makes for clean spreadsheets, but real portfolios swing from year to year, and the sequence example above shows how two identical sets of returns can leave very different balances depending on timing. Testing your plan against a bad start, not just an average one, gives you a more honest picture. Forgetting that the monthly number is before taxes. If most of your savings sit in traditional IRAs or 401(k)s, your withdrawals count as taxable income (3) , so a $1,667 withdrawal won’t arrive as $1,667 of spending money. What’s the next step for your own numbers? The figures in this article are a hypothetical starting point, resting on clearly labeled assumptions that probably don't match your situation exactly. Your own monthly number depends on when you plan to stop working, when you'll claim Social Security, which accounts your money sits in, and how much flexibility you have if markets turn against you early. If you've been looking at your balance and wondering whether it will cover the life you've been planning, a conversation with a professional who can test your own numbers against different scenarios can turn that question into a plan. References 1. William P. Bengen. "Determining Withdrawal Rates Using Historical Data." Journal of Financial Planning, October 1994, reprinted by the Financial Planning Association, March 2004. https://www.financialplanningassociation.org/sites/default/files/2021-04/MAR04%20Determining%20Withdrawal%20Rates%20Using%20Historical%20Data.pdf 2. Morningstar. "What's a Safe Retirement Withdrawal Rate for 2026?" https://www.morningstar.com/retirement/whats-safe-retirement-withdrawal-rate-2026 3. Internal Revenue Service. "Retirement Topics: Required Minimum Distributions (RMDs)." https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-required-minimum-distributions-rmds 4. Internal Revenue Service. "Publication 590-B (2025), Distributions from Individual Retirement Arrangements (IRAs)." https://www.irs.gov/publications/p590b 5. Internal Revenue Service. "Topic No. 409, Capital Gains and Losses." https://www.irs.gov/taxtopics/tc409 6. Social Security Administration. Monthly Statistical Snapshot, August 2026.” https://www.ssa.gov/policy/docs/quickfacts/stat_snapshot/2026-08.html ” 7. Morningstar. “The State of Retirement Income for 2026.” https://www.morningstar.com/business/insights/research/the-state-of-retirement-income All dollar figures in this article are hypothetical illustrations based on a $500,000 starting balance and the assumptions stated with each example, including constant annual returns, a 2.5% annual inflation rate, and a 12% federal tax rate where noted. They are not projections of any investment's performance. The safe withdrawal rate reflects Morningstar's State of Retirement Income research for retirees starting withdrawals in 2026. RMD distribution periods reflect the IRS Uniform Lifetime Table in Publication 590-B. The average Social Security benefit reflects SSA data for August 2026. All sources were verified against their live pages on October 7, 2026. General information: This article is for general educational purposes only and isn't investment, tax, or legal advice. The examples are illustrations, not recommendations, and your own results will depend on your investments, taxes, spending, health, and how long you live. Consider speaking with a qualified financial professional or tax advisor about your specific situation before making withdrawal decisions. Investment disclaimer: Nothing on this site constitutes investment advice. All investors are encouraged to conduct their own research before making any investment decision. Past performance is not a guarantee of future results. Editorial independence: Greensprout's editorial team writes on behalf of the reader. Our goal is to provide clear, useful information to help you make better financial decisions. Our editorial content is not influenced by advertiser relationships. Affiliate disclosure: Greensprout is an independent, advertising-supported publisher and comparison resource. We may earn compensation when you click on links to products from our partners. This does not affect our editorial standards or recommendations.