Key takeaways
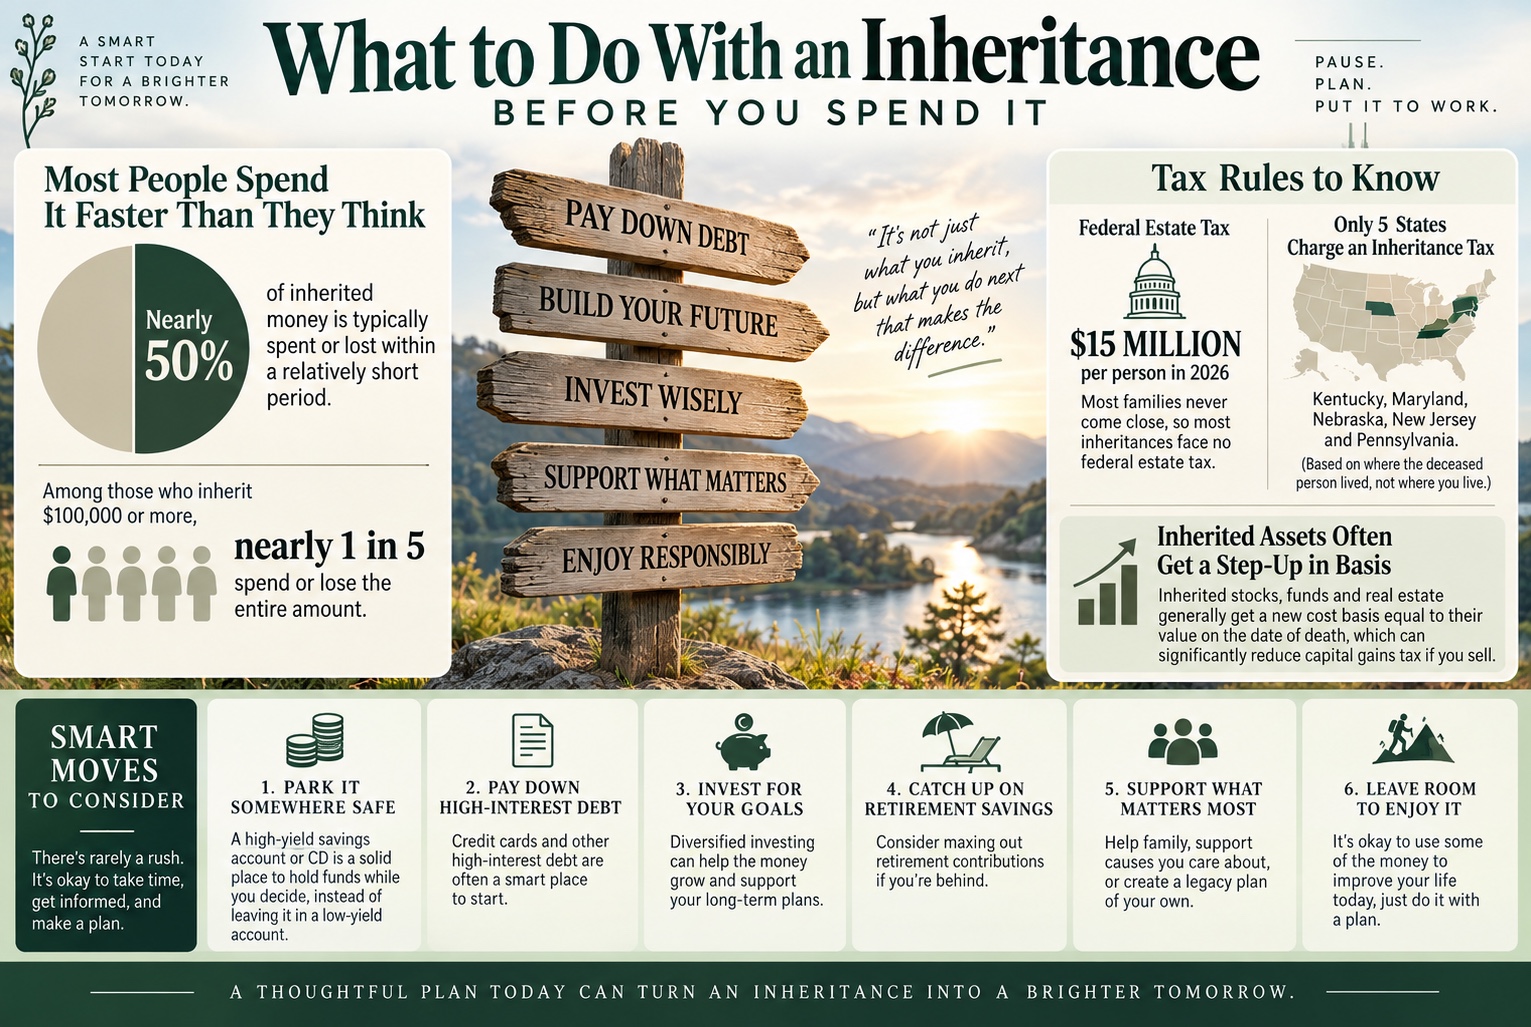
- Only five states charge an inheritance tax on recipients as of 2026, and the rule depends on where the deceased person lived, not where you live.
- Inherited retirement accounts follow different rules than your own.
- A high-yield savings account or CD is a reasonable place to hold funds while you decide, rather than leaving them in a low-yield account by default.
- Paying off high-interest debt, catching up on retirement contributions, and diversified investing are among the most commonly recommended categories.
An inheritance rarely arrives at a convenient moment. You are usually still grieving, often still handling paperwork for someone else's estate, and now a lump sum lands in an account with your name on it. Relatives start asking what you plan to do with it. A financial advisor you have never met might call. And somewhere in the back of your mind is a number, maybe modest, maybe life-changing, that suddenly makes almost anything feel possible.
That feeling is exactly where trouble tends to start. The pressure to decide fast, the instinct to fix every financial worry at once, and the discomfort of holding an unfamiliar sum of money all push people toward decisions they would not make with money they had earned and saved themselves. This guide will not tell you the one ‘right’ money move, instead it lays out the categories of options people typically weigh with inherited money, tax rules that can shape which ones make sense for you, and the reasoning behind each so you can make an informed call with your own family, your own state, and your own goals.
Why does inherited money disappear so fast?
Researchers have studied this question directly, and the data is not encouraging. A 2026 study in the peer-reviewed journal Financial Services Review, using federal Health and Retirement Study data on more than 4,000 windfalls, found that 42% of people who inherited money had spent the entire amount within about a year, measured at the next survey wave(1).
After adjusting for inheritances being roughly three times larger than other windfalls like lawsuit settlements or gifts, the researchers found inheritors were 24% more likely to spend the whole amount immediately than people who received other types of windfalls of the same size(1).
Each inherited dollar increased a person's net worth roughly a year later by only 61 cents, on average(1).
Part of what makes an inheritance different from money you saved yourself is timing. It shows up during a period of loss, often alongside estate paperwork, family dynamics, and decisions that feel urgent even when they are not. Advisors who work with wealth transfer describe this cluster of stress, decision paralysis, and pressure from people around you as a real and common pattern, not a personal failing.
The good news is that none of this requires an immediate decision. Beyond a few time-sensitive tax elections, which this guide covers below, there is rarely a deadline that forces you to invest, spend, or commit inherited money within days or weeks of receiving it. Parking the funds somewhere safe while you think it through is itself a legitimate first option, and probably the one most people underuse.
Does your state take a cut before you even decide?
Before weighing where to put the money, it helps to know whether anyone else has a claim on it first. Two different taxes get confused constantly here, and knowing which one applies changes how much you have to work with.
An estate tax is charged against the estate itself, before anything gets distributed to heirs, based on the total value of what the deceased person owned. An inheritance tax works differently. It is charged to you, the person receiving the money, and the rate depends on how closely related you were to the person who died.
At the federal level, only very large estates owe anything.
The federal estate tax exemption rose to $15 million per person for 2026, up from $13.99 million in 2025, after Congress made the higher threshold permanent rather than letting it roll back(2). Most families never come close to that number, so many inheritances face no federal estate tax at all. State rules are where the real variation shows up.
As of 2026, only five states still charge an inheritance tax on the recipient:
- Kentucky
- Maryland
- Nebraska
- New Jersey
- Pennsylvania(2)
Iowa repealed its inheritance tax entirely for deaths occurring on or after January 1, 2025, after several years of phasing the rate down(2). In every one of the remaining states, spouses are fully exempt, and many extend that exemption to children as well, with Pennsylvania as a notable exception. Pennsylvania charges a 4.5% inheritance tax on what direct descendants, including children and grandchildren, receive, with no exemption for that relationship, a detail that surprises a lot of families who assume "immediate family" always means tax-free(3).
Separately, twelve states plus Washington, D.C. levy their own estate tax on top of the federal one, with exemption thresholds that are far lower than the federal amount. Oregon's exemption sits at just $1 million, and several other states fall in the $2 million to $7 million range, meaning an estate that owes nothing federally can still trigger a state estate tax bill(2). Maryland is the only state that imposes both an estate tax and an inheritance tax on the same transfer.
Which tax applies to you typically depends on where the person who died lived and where their real estate was located, not where you live.
A resident of a no-tax state like Florida who inherits from a parent who lived and died in Pennsylvania can still owe Pennsylvania inheritance tax. If you are unsure whether a state tax applies to what you received, that is worth confirming with the estate's executor or a tax professional before you assume the full amount is yours to allocate.
What kind of asset did you inherit?
Options depend on what form the inheritance takes, because the tax treatment is not the same across asset types.
Cash or a brokerage account. If you inherited stocks, mutual funds, or a taxable investment account, those assets typically receive what is called a step-up in basis. Under Section 1014 of the tax code, the cost basis of most inherited capital assets resets to their fair market value on the date the original owner died(4). In practice, that means decades of embedded appreciation can disappear for tax purposes. If a parent bought stock for $20,000 and it was worth $300,000 when they died, your basis becomes $300,000. Sell it soon after and you owe little or nothing in capital gains tax, even though the original owner would have owed a substantial amount had they sold it themselves. This step-up also applies to real estate and closely held business interests.
A retirement account like a traditional or Roth IRA. This is where a lot of people run into confusion, because inherited retirement accounts do not follow the same rules as your own. Non-spouse beneficiaries are generally required to empty an inherited IRA within ten years of the original owner's death, a rule that replaced the old "stretch IRA" option under the SECURE Act(5). If the original owner had already started required minimum distributions before they died, you may also owe annual minimum withdrawals during years one through nine, not just a final withdrawal in year ten, a requirement the IRS confirmed in final regulations that took effect for distributions beginning in 2025(6). Every dollar withdrawn from an inherited traditional IRA is taxed as ordinary income in the year you take it, so a single large withdrawal near the end of the ten-year window can push you into a higher tax bracket. Spreading withdrawals more evenly across the ten years is often more tax-efficient than waiting. Spouses have more flexibility and can generally roll an inherited IRA into their own.
A house or other real estate. Like a brokerage account, inherited real estate gets the same step-up in basis, which is worth understanding before you plan to sell rather than keep it. Holding onto a family home comes with its own set of ongoing costs and decisions that go beyond this guide's scope, but the tax basis reset is worth knowing before you talk to anyone about selling.
Where do you keep the money while you decide what to do with it?
Once you know what you received and what, if anything, a state or the IRS is owed, the next practical question is where to keep the funds during the weeks or months you spend deciding. This is not a permanent investment decision. It is a holding pattern.
The most common mistake here is leaving the money in a checking account or the same savings account it landed in, which at most large banks pays close to nothing. The national average savings account rate was 0.38% as of mid-2026, according to FDIC data, while many online high-yield savings accounts were paying close to 4% on the same balance(7).
On $100,000, that difference comes out to roughly $380 a year in one account versus roughly $4,000 in the other, for doing nothing more than opening a different type of account. A high-yield savings account keeps the money liquid, insured up to $250,000 per depositor per institution through the FDIC, and earning something while you decide what comes next. For a larger inheritance, spreading deposits across more than one institution keeps the full balance within FDIC coverage.
Certificates of deposit (CD’s) are another option worth understanding for this holding period, particularly if part of your decision-making timeline is fixed, such as knowing you will need a portion of the funds in twelve or eighteen months. A CD locks in a fixed rate for a set term in exchange for a penalty if you withdraw early, which trades some flexibility for a yield that is often slightly higher than a savings account.
Is paying off debt on the table?
For many people, the most straightforward category of options is not investing at all, but eliminating debt that is working against them. Credit card debt is the clearest example. The average credit card interest rate stood at roughly 20 to 21% as of 2026, according to Federal Reserve data(8). No investment option covered in this guide reliably returns 20% a year, which is why financial educators often frame paying off high-interest debt as a guaranteed return equal to the interest rate you stop paying.
The same logic applies with less force to lower-rate debt. A mortgage at 6% or a car loan at 7% does not carry the same urgency, and paying it off early means giving up the flexibility of having that cash available for other goals. This is a genuine tradeoff rather than an obvious answer, and it depends on your interest rate, your other savings, and how much you value being debt-free versus keeping funds liquid.
Does catching up on retirement make sense?
If retirement savings and investing have lagged behind where you would like them to be, an inheritance is one of the few realistic ways to accelerate that without changing your income. The mechanism is contribution room, not a special inheritance-specific account. For 2026, the IRA contribution limit is $7,500, with an additional $1,100 catch-up contribution available if you are 50 or older, for a total of $8,600(9).
Workplace plans like a 401(k) allow considerably more, with a $24,500 limit in 2026, plus an $8,000 catch-up for those 50 and older, and a higher catch-up of $11,250 for people specifically between 60 and 63(9). You can learn more about catch up contributions here.
An inherited lump sum cannot be dropped directly into an IRA or 401(k) the way a stock portfolio transfers, because contributions to these accounts are capped by your own earned income, not by how much cash you have on hand. What the inheritance can do is free up your regular paycheck to be redirected toward maxing out those accounts, using the inherited funds to cover living expenses in the meantime. This is a slower path than it might sound, but it is one of the more tax-advantaged uses of the money for anyone behind on retirement savings.
A health savings account plays a similar role if you have a high-deductible health plan. HSA contributions are deductible going in, grow tax-free, and come out tax-free for qualified medical expenses, a combination sometimes called triple tax advantage. The 2026 contribution limit is $4,400 for individual coverage and $8,750 for family coverage, with an additional $1,000 allowed for anyone 55 or older(10).
What about investing the rest?
For money that is not earmarked for debt, retirement catch-up, or a near-term need, a taxable brokerage account holding a diversified mix of index funds is the option many financial educators point to for long-term growth. The appeal for inherited money specifically is that a diversified fund spreads risk across hundreds or thousands of companies, rather than concentrating an unfamiliar sum in a handful of positions the way a single inherited stock can.
This is also where the step-up in basis discussed earlier becomes relevant to a decision, not just a tax fact. If you inherited an individual stock, its basis reset to the value on the date of death, which means you can sell it and reinvest into a more diversified mix without triggering the capital gains tax the original owner would have faced. Whether to sell and diversify or hold the specific investment you inherited is a personal call that depends on your comfort with concentration risk and your view of that particular company, but the tax cost of making the switch is often lower than people assume.
Is there a place for education savings or charitable giving?
If part of your reason for saving is a child's or grandchild's education, a 529 plan offers tax-free growth for qualified expenses. Since 2024, families also have a new form of flexibility here, since up to $35,000 over a beneficiary's lifetime can be rolled from a 529 into that same person's Roth IRA if the account has been open at least 15 years, subject to annual Roth contribution limits(11).
For those inclined toward charitable giving, a donor-advised fund lets you contribute a lump sum now, take the tax deduction in the year you fund it, and decide which charities to support over time rather than all at once. This can be a way to honor the person you inherited from without needing to finalize every giving decision immediately.
Where do people usually go wrong?
Treating an inherited IRA like your own. The ten-year withdrawal window and its tax treatment surprise many people who assume they can leave the account alone indefinitely the way the original owner could. You can learn more about inherited IRA’s here.
Letting the state tax question go unanswered. Assuming no tax applies because you live in a state with no inheritance tax ignores the rule that the deceased person's state, not yours, generally determines what is owed.
Leaving a large amount of money in a low-yield account for months out of indecision. A holding period is reasonable. Leaving tens of thousands of dollars earning close to nothing for a year is a cost, even if it does not feel like one. High Yield Savings Accounts are a good option to earn a little cash while you decide what to do while keeping your money fully accessible.
Selling an appreciated inherited asset without checking the tax implications first. Some heirs pay unnecessary capital gains tax because they assume the original cost basis applies, when the step-up rule may have already reset it to close to the sale price.
Every situation here depends on the size of the inheritance, the state involved, and what you were already doing financially before the money arrived. Comparing your options against your specific numbers, ideally with a fee-only financial advisor who does not earn a commission on what you choose, is the most reliable way to turn this guide into an actual plan.
Where do you go from here?
Every option in this guide comes with tradeoffs that depend on details specific to you: your state, your age, your existing debt, and what the person who left you this money would have wanted for it. A short questionnaire can match you with a vetted financial advisor suited to your situation, so you get guidance built around your specific numbers rather than a general answer.
Find the right financial advisor for your situation
References
1. Thompson, C., & James, R. III. (2026). "Dissipation of Inheritance Windfalls and the Case for Time-Phased Transfers: An Empirical Assessment From HRS Data." Financial Services Review, 34(1), 24-42. https://doi.org/10.61190/fsr.v34i1.4307
2. Tax Foundation. "Estate and Inheritance Taxes by State, 2025." https://taxfoundation.org/data/all/state/estate-inheritance-taxes/
3. Commonwealth of Pennsylvania, Department of Revenue. "Inheritance Tax." https://www.pa.gov/agencies/revenue/resources/tax-types-and-information/inheritance-tax
4. Internal Revenue Code Section 1014, Basis of Property Acquired From a Decedent. https://www.law.cornell.edu/uscode/text/26/1014
5. Fidelity. "Inherited IRA Rules Explained." https://media.fidelity.com/assets/Fidelity.com_VMS/742/223/Inherited_IRA_rules_explained_Fidelity.pdf
6. Federal Register. "Required Minimum Distributions," final rule, 89 FR 58886, effective September 17, 2024, applicable for distribution calendar years beginning on or after January 1, 2025. https://www.federalregister.gov/documents/2024/07/19/2024-14542/required-minimum-distributions
7. The Motley Fool. "Average Savings Account Interest Rate," July 2026, citing FDIC data. https://www.fool.com/money/research/average-savings-account-interest-rate/
8. Experian. "Current Credit Card Interest Rates," September 2026, citing Federal Reserve G.19 data. https://www.experian.com/blogs/ask-experian/research/current-credit-card-interest-rate/
9. Internal Revenue Service. "401(k) limit increases to $24,500 for 2026, IRA limit increases to $7,500," IR-2025-111, Nov. 13, 2025. https://www.irs.gov/newsroom/401k-limit-increases-to-24500-for-2026-ira-limit-increases-to-7500
10. Fidelity. "401(k) Catch-Up Contributions for High Earners," citing 2026 HSA contribution limits. https://www.fidelity.com/learning-center/personal-finance/401k-catch-up-contributions-high-earners
11. Fidelity. "Understanding 529 Rollovers to a Roth IRA." https://www.fidelity.com/learning-center/personal-finance/529-rollover-to-roth
Tax and contribution figures reflect 2026 rules as of publication and are indexed for inflation annually. State inheritance and estate tax rules change periodically; confirm current rules for your specific state before making decisions. This article is educational and does not constitute tax, legal, or investment advice.